No hawkish shift as rates stay on hold Mexico’s central bank (Banxico) left interest rates unchanged again today, at 6.50%, and the communications suggest that Banxico is likely to remain on hold. But we think the balance of factors will shift Banxico in …
24th September 2026
While JGBs have been caught up in the latest chapter of the global bond market rout, we don’t expect them to continue to come under a lot of fire. The latest sell-off in JGBs, which has taken the 10-year yield decisively above 3% for the first time in …
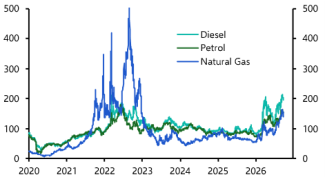
It now seems more likely than not that some form of export restriction of US diesel will come into place ahead of the midterms which will exacerbate the ongoing diesel “shock”. Most refineries have limited capacity to further ramp up diesel supply, but …
China’s influence on headline inflation in advanced economies has been much smaller than is often assumed, given the dominant weight of services in consumer spending. But its surging exports have had a strong impact on the price of certain manufactured …
Overview – The ongoing strength in AI investment should help to offset the hit to real incomes from the renewed rise in fuel prices, resulting in above-consensus GDP growth of 2.5% next year. That will lead to tighter labour market conditions and keep …
Our China Activity Proxy suggests that growth remained in the doldrums in August amid a contractionary fiscal stance and continued typhoon disruptions. Growth should recover soon as fiscal spending picks back up, but it’s looking increasingly likely that …
Corporate bond issuance by AI-related firms has surged over the past year, particularly at the long end of the curve. This could push up Treasury term premia before long if it continues at this rate, although it probably hasn’t done so by much so far. …
Rates on hold, cuts unlikely until next year The Central Bank of Egypt left its policy rate unchanged at 19.00% for a fifth consecutive meeting today and, while we think rate hikes are unlikely, the backdrop of high global energy prices means that the …
The improvement in the survey indicators bodes well for hiring in September, while payrolls should also benefit from a reversal of the seasonal effects that weighed on hiring at the start of the summer. We have pencilled in a 100,000 gain, with the …
Global bond markets have taken a big hit in recent months, but French government bonds have been singled out. We think this makes sense given the widening fiscal deficit and the growing risks around next April’s presidential election. Indeed, there is a …
Retail sales volumes struggling for momentum ahead of latest gasoline price surge The larger-than-expected 1.1% m/m fall in retail sales volumes in July isn’t the end of the world, given the advance indicator implies that sales volumes fully rebounded in …
It’s a misconception that lower Treasury yields are essential to solving the US debt problem . Admittedly, Treasury yields may fall if, as we saw in the 1990s, the solution mainly involves fiscal consolidation. But Treasury yields may ultimately rise if, …
Pipeline partially re-opens Saudi Arabia’s key East-West oil pipeline is back in partial operation after a drone attack forced its closure almost two weeks ago. Reuters reported news of the restart on Tuesday, providing some relief to energy markets – …
A higher path for interest rates means we now expect euro-zone all-property yields to rise by 15-20bps over the next 6-12 months. The risk of increases appears greatest in Paris, where the property-to-bond yield spread is both narrow by recent standards …
Overview – The euro-zone economy is likely to continue growing at around its trend rate of 1% over the next year or two. Among the largest countries, Germany, France and Italy will grow at a modest pace while Spain will continue to outperform, …
With the conflict in the Middle East constraining OPEC’s influence on oil supply, changes in Chinese oil demand have become the “swing” factor in the global oil market. China probably could cut back on crude oil imports again, but the risk is that the …
High-frequency data suggest that the rise in US Treasury yields has triggered capital outflows from EMs. But so far at least, the shift has been relatively gradual. Taken together with strong external balance sheets, these outflows are unlikely to trigger …
The SNB’s decision to leave interest rates on hold today was in line with economists’ and investors’ expectations. But in contrast to the prevailing view in the market that the Bank will hike rates at least three times by the end of 2027, we think it will …
German Ifo Survey (September 2026) More evidence that Germany is growing steadily September’s improvement in the German Ifo Business Climate Index (BCI) follows a sharp increase in the PMI published yesterday and provides more evidence that the economy is …
Rates will peak at 4.60% A solid rebound in employment in August didn’t prevent the jobless rate from rising again. With the labour market likely to cool even further in the coming months, we think the RBA’s 25bp hike next Tuesday will be the last in the …
The outbreak of the Iran war has threatened Dubai’s status as the Gulf’s pre-eminent financial and commercial hub, but there are already tentative signs of recovery in its economy. The pace and durability of this will depend in part on how quickly …
23rd September 2026
The spread between the 10-year French and German government bond yields has reached its widest level in over a decade, and we think it will widen further next year as investors’ concerns about France’s public debt burden grow. France’s 10-year government …
This report is part of our new series on China Shock 2.0. Explore the series and follow the latest publications on this dedicated page . The ideal solution to the unsustainable fiscal situation is that Congress commits to a gradual fiscal adjustment. …
The South African Reserve Bank (SARB) chose to restart monetary tightening with a 25bp hike to 7.25% today, but the commentary suggests that this hiking cycle may already be over. Higher energy prices or the emergence of second round effects could change …
The renewed rise in mortgage rates reinforces our view that housing starts will fall further in the coming years, keeping downward pressure on residential investment. This does not imply an impending drop in construction employment, however, given hiring …
A ban on diesel exports by the US would exacerbate the existing severe strains in the global diesel market and drive prices outside of the US even higher in the short term. Nonetheless, given that a surplus of diesel in the US could paradoxically force …
This page has been updated with additional analysis since first publication. Renewed inflationary pressures cement BoE’s tilt towards higher interest rates September’s flash PMIs suggest the resilience in activity may have faded a touch in Q3, but …
Emerging Europe Chart Pack (September 2026) …
Soft inflation strengthens case for a hold later today The smaller-than-expected rise in South African inflation in August, to 4.4% y/y, and signs of softer underlying inflation pressures will be welcome news for SARB officials. It will be a close call, …
Activity growing, price pressures building but no second-round effects September’s big improvement in the euro-zone’s composite PMI supports our view that despite the weakness in the official activity data in July, GDP will increase in Q3. The output …
Overview – The RBA will deliver another 25bp hike in September, given continued stickiness in underlying inflation. But unlike markets we doubt further tightening will prove necessary. With the labour market cooling and the housing downturn going from bad …
Rates on hold, but rupiah back in the spotlight Bank Indonesia left its policy rate on hold at 5.75% today and, so long as the recent falls in the rupiah don’t morph into a sharp sell-off, we think interest rates will be left unchanged over the remainder …
Overview – A decisive end to the Iran war is still far away and, as a result, the economic recovery in the Gulf will be slow and bumpy. A return to pre-war energy exports is unlikely until at least early next year and non-oil activity will be held back …
22nd September 2026
After a very strong first half of the year, India’s economy is set to cool but annual GDP growth should still average an impressive 7% from 2026-2028. Rising food prices on account of a weak monsoon will push headline inflation to the upper bound of the …
A negative yield impact outweighed rental growth in August, meaning all-property capital values recorded a year-on-year decline for the first time since late 2024. But we still think the 10-year gilt yield will fall back next year, and a significant …
Brazil’s next government will inherit a fiscal position that requires fiscal tightening to the tune of 3.0% of GDP to stabilise the public debt ratio. A Bolsonaro victory would offer a path towards more fiscal credibility and deliver a relief rally in …
The Central Bank of Nigeria’s (CBN) surprise decision to cut its policy rate by 350bp today, to 23.00%, underlines its confidence that the disinflation process will continue over the coming months. With real interest rates still high, but the CBN mindful …
That AI-related stock market sectors have tended to fare best when oil prices have tumbled partly reflects their high market betas and, increasingly, their sensitivity to bond yields as AI-related debt issuance mounts. The large fall in Brent crude oil …
Hungary’s central bank (MNB) opted to leave its base rate on hold at 5.50% today, and the decision to lower the inflation target to 2.5% from 2028 argues for a more cautious approach to renewed rate cuts than would otherwise be the case. We think the …
Energy shock weighing on consumer sentiment September’s decline in consumer confidence shows that households’ moods have soured as energy prices have risen. But as long as oil and natural gas prices don’t rise a lot further, we think household consumption …
Easing cycle on pause, all eyes on the new inflation target Hungary’s central bank (MNB) opted to leave its base rate on hold at 5.50% today and the easing cycle will probably be on pause through the rest of this year as the central bank introduces a new, …
A decisive end to the Iran war is still far away, exports are disrupted and energy prices are climbing. On Wednesday 30th September , our MENA and Commodities teams hosted a special briefing to discuss the health of the Gulf economies and the legacies of …
21st September 2026
This report is part of our new series on China Shock 2.0. Explore the series and follow the latest publications on this dedicated page . China’s ability to produce and export green technologies at a low cost is a key driver of renewable and electric …
Despite productivity gains that could reduce the need for office space, markets with a high share of information and communication jobs have generally seen stronger office take-up over the past year . However, the risk is that this does not last. Our …
Fuel subsidies and price controls have stopped high oil prices from feeding into inflation across Asia’s largest economies. But this has not eliminated inflation concerns altogether and, in India and Japan, we expect tightening cycles to be more …
RBA will hike rates to 4.60% as inflation risks come to the fore But labour market cooling should make September the last hike Rate cuts to begin from the second half of next year With some of the upside inflation risks it had warned about now …
This page has been updated with additional analysis since first publication. Dismal backdrop for the Autumn Budget The penultimate public finances release before the Budget on 28 th October paints a dismal picture, with the government once again borrowing …
The big risk after the midterms is that emboldened Democrats try to leverage the debt ceiling to achieve their policy aims, raising the possibility of a debt default. Admittedly, Republicans may lift the debt ceiling while still in control of Congress. …