Our senior economists from our US, Europe and UK teams hosted our regular dive into the latest decisions and communications from these leading monetary authorities on Thursday 29th October. In this concise online briefing, the team answered your questions …
23rd October 2026
Fiscal progress, but the bond rally faces hurdles Hungary’s long-awaited 2027 budget delivered a positive surprise for investors, but there are doubts about whether the government can deliver on its ambitious medium-term fiscal targets. The government …
We’ll be discussing what was announced in the Budget and what it means for the economy and markets in a 20-minute online session at 3pm GMT on Wednesday 28 th October. (Register here . ) This page has been updated with additional analysis since first …
Indonesia’s President Prabowo marked two years in office this week and, while the headline economic figures look good, his populist, interventionist approach to governing poses risks to Indonesia’s macro stability and long-term prospects. On the face of …
Activity still robust, little evidence of second-round effects Although the euro-zone’s composite PMI fell in October, it remains consistent with modest positive growth, suggesting that the economy has remained resilient in the face of the energy shock. …
The US lead in AI computing is hard to close China’s AI computing capacity continues to expand rapidly. But with the US already far ahead and investing heavily, while domestic firms suffer from more limited access to AI chips, China risks falling further …
We’ll be discussing what was announced in the Budget and what it means for the economy and markets in a 20-minute online session at 3pm GMT on Wednesday 28th October. (Register here .) This page has been updated with additional analysis since first …
November decision hangs in the balance At a fireside chat this week, RBA Deputy Governor Andrew Hauser made some distinctly hawkish comments that set markets on edge. Indeed, investors are now pricing in a roughly three-fifths chance of 25bp hike in …
Higher energy prices barely register External trade data released this week showed that the trade deficit narrowed in September. Indeed, it remains far lower than it was during the previous energy cost shock in 2022. (See Chart 1.) Granted, crude oil …
Bank will hike again in December amidst continued concern about strong inflation With financial conditions still loose, risks are shifting towards a higher peak in rates For now though, we’re sticking to our long-held view that rates will peak at 2% …
Bank of Japan on course to tighten further With underlying inflation back above the Bank of Japan’s 2% target, the case for further tightening remains on solid ground. Headline inflation picked up from 1.9% in August to 2.1% in September, in line with the …
BoK on hold, one further hike left in the cycle The Bank of Korea (BoK) left its policy rate unchanged at 3.00% at today’s meeting, but we doubt this marks the end of the tightening cycle, and have pencilled in one hike for the BoK’s final meeting of the …
22nd October 2026
October hold looks all but certain despite inflation risks Upcoming midterm elections will have had no bearing on the decision 25bp December hike remains highly likely; we expect one additional hike after that Although the latest hot inflation readings …
Although S&P 500 earnings per share (EPS) have grown far more quickly than the US economy since the start of the AI revolution, this isn’t bound to last even if Q3 2026 is another bumper earnings season. As the earnings season gets into full swing, it’s …
We will be reacting to the meeting in an online briefing at 5pm GMT/1pm ET on Wednesday 28th. Register here . Balance of risks has shifted towards higher inflation over lower growth Bank will tighten to quell resurging inflation expectations Excess …
Strong AI-related investment and resilient consumption should cause GDP growth to rebound in the third quarter and maintain a growth rate of about 2.5% in the coming year. Despite the recent slowdown in employment growth, we expect the unemployment rate …
We expect limited immediate market reaction if Flavio Bolsonaro wins Sunday’s run-off election. Over the medium term, though, the bond rally may continue if the Selic rate is cut by more than money markets currently discount and Bolsonaro delivers …
Emerging Europe has weathered the energy shock well and we expect regional growth to strengthen in 2027. We remain upbeat on growth in Poland and Czechia, but more cautious than the consensus on Russia, Romania and Turkey. Monetary policy cycles will …
Japan’s emerging yttrium shortage illustrates the broader vulnerability created by China’s dominance of rare earth supply. The immediate economic impact appears limited, but disruption could intensify and spread beyond Japan through global supply …
Disinflation to bring interest rates down further The Turkish central bank (CBRT) started its rate cutting cycle with a 100bp reduction in the one-week repo rate to 36.00% today and, with inflation pressures subsiding, we expect an additional 850bp of …
After a very strong run, India’s economy is set to cool but annual GDP growth is still on course to average an impressive 7% from 2026-2028. Rising food prices on account of a weak monsoon will push headline inflation above the upper bound of the RBI’s …
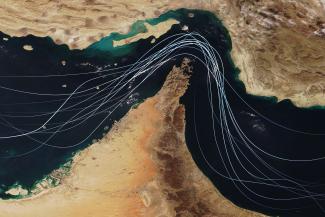
Gulf energy flows resilient in face of Iran attacks Reports this week suggest that crude oil flows from the Gulf have returned to pre-war levels. That’s been helped by the use of ship-to-ship transfers as well as the utilisation of pipelines in Saudi …
China's rapidly expanding trade surplus is the clearest sign of a widening in external imbalances on a scale not seen since the mid-2000s. But how much of a risk do they pose to global macro stability, how long will they persist, and how disruptive would …
1st October 2026
With inflation pressures building, labour cost growth remaining high and credit growth strong, the conditions appear to be in place for the Czech central bank (CNB) to continue its tightening cycle at its upcoming meeting. We maintain our forecast for a …
The unusually low share of take-up in the main German industrial hubs appears to reflect a shortage of available space rather than weak demand. While space under construction is rising, this is not likely to be enough to change this dynamic. Therefore, we …
BSP delivers bumper 50bp hike, tightening probably over The Bangko Sentral ng Pilipinas (BSP) hiked interest rates today by a larger-than-expected 50bp, to 5.50%, but so long as energy prices stabilise and drop back from early next year as we assume, …
The Bank of Korea (BoK) kept its policy rate unchanged at 3.00% today. But the tone of its statement and the decision to raise its growth forecasts for this year and next suggest that the tightening cycle is not over. We expect one more 25bp hike, most …
We expect the RBNZ to lift the Official Cash Rate by 25bp, to 3.00%, at its October meeting, as it seeks to mitigate upside risks to inflation. We’ve also brought forward our forecast for the final 25bp hike from March to December, as the Bank presses …
Rising core inflation raises risk of more aggressive tightening The pullback in headline inflation in Q3 won’t provide much comfort to the RBNZ, given that underlying price pressures continued to build. The 0.7% q/q rise in consumer prices last quarter …
21st October 2026
Gilts have been out of the spotlight of late as investors’ focus has been on the US and France and it is likely to stay that way as the Chancellor delivers a low-key Budget next week. We expect Gilt yields to fall over the next year as the energy shock …
South Africa’s finance minister announced in today’s Medium-Term Budget Policy Statement (MTBPS) that the revenue windfall had persisted, allowing him to cover higher debt servicing costs and lift non-interest spending. As a result, fiscal consolidation …
Pause in the cycle, but still a little scope for further easing The Bank of Israel (BoI) kept interest rates on hold at 3.25% as expected today and we think it will adopt a more cautious stance towards further easing going forward. This points to perhaps …
Thailand has long been South East Asia’s leading automotive production hub, built around Japanese manufacturers and a deep network of local suppliers. But the shift towards EVs is reshaping its passenger-car industry, even as Chinese investment offers a …
A resurgence in oil prices and renewed trade tensions with the US have put the Bank of Canada’s upcoming policy rate decision on a knife-edge. Amid historic levels of uncertainty, Governing Council must decide whether the upside risks to inflation finally …
The lack of an aggressive supply response from US oil producers reflects uncertainty over the price outlook and large producers’ preference for returning higher free cash flow to investors. Looking ahead, it’s unlikely that US producers will raise output …
The UK government’s decision to allow production at the Jackdaw North Sea gas field is unlikely to have a material impact on the UK economy. It should provide a modest boost to domestic gas production, exports and the current account, while improving …
ECB likely to leave its deposit rate at 2.5% next week. We forecast a final hike in this cycle, in December. President Lagarde will not offer a lifeline to France. The latest evidence suggests that the euro-zone economy remains fairly resilient in the …
For all the talk of the “death of forward guidance”, central banks are still providing a clear steer of how policy will respond under given circumstances. If the energy shock fades as we assume, the BoE and ECB seem likely to reverse course relatively …
Bahrain probably requires the other Gulf countries to pledge further financial support in order to sustain its dollar peg and roll over maturing external debt. We remain of the view that this will be forthcoming, not least because the rest of the Gulf …
Softer underlying inflation weakens the case for more rate hikes The smaller-than-expected rise in South African inflation in September, to 4.5% y/y, and signs of softer underlying inflation pressures will be welcomed by the SARB. High global energy …
Mixed policy messages risk undermining Bank Indonesia’s credibility The policy moves by Bank Indonesia today suggest that officials are struggling to work out whether to prioritise supporting the rupiah or boost growth. These mixed messages risk …
Official GDP growth picked up in Q3, but the improvement masks a further weakening in domestic demand. The detailed breakdown suggests that last quarter’s rebound was driven entirely by net exports, while even the AI-related boost to growth is becoming …
This page has been updated with additional analysis since first publication. Tentative signs higher energy prices are feeding into non-energy inflation The rise in CPI inflation from 3.1% in August to 3.5% in September (consensus 3.4%, CE forecast 3.6%) …
While renewed hopes of a peace in the Middle East and lower energy prices have brought some relief to government bond markets today, the widening of the spread between French sovereign bonds and those in the rest of the euro-zone probably has further to …
20th October 2026
The surge in mortgage rates in recent months has brought housing activity to a standstill, as shown by the collapse in pending home sales in September to their lowest level since the series began. Seasonally adjusted pending home sales – also known as …
Growth in the region appears to have weakened sharply in Q3 and, if anything, the risks to our below-consensus forecasts may now lie to the downside. High inflation across the region limits the extent to which central banks can provide …
Surge in mortgage rates weighs on starts The sharp decline in both single- and multifamily housing starts in September reflects homebuilders’ reluctance to start new projects amid the latest surge in mortgage rates, which will continue to suppress …
MNB to stay on hold despite soft inflation Hungary’s central bank (MNB) decided to leave its policy rate unchanged at 5.50% today despite further downside inflation surprises. We see the MNB opting for a prolonged pause in rates as it seeks to anchor …
Having already driven the US stock market over recent years, the AI theme is increasingly driving the Treasury market too. We expect this to remain the case over the coming year: we forecast a plunge in US equities to help fuel a further rally in …