This report is part of our new series on China Shock 2.0. Explore the series and follow the latest publications on this dedicated page.
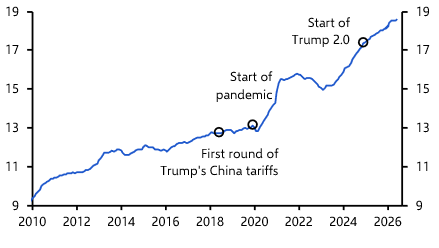
A key difference between the first China Shock in the mid-2000s and the China Shock today is that China now stands as a strategic competitor to the US. This gives the latest China shock a geopolitical dimension that was largely absent from the original one.
One consequence is that policymakers and firms are increasingly having to think about economic resilience, not just economic efficiency. Beijing’s decision last year to restrict exports of critical minerals in retaliation to US economic pressure demonstrated its willingness to use its dominance in particular industries as a source of leverage against geopolitical competitors.
Unpacking “resilience”
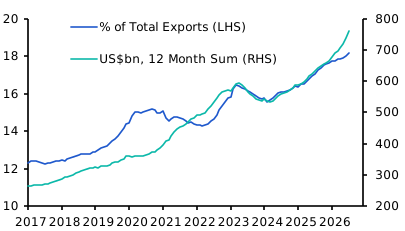
Two distinct, albeit related, concerns are often lumped together under the heading of “economic resilience”. The first is the supply-chain dependency created by China’s growing dominance of the production of inputs and finished goods across a wide range of industries. China accounts for over 90% of global production of refined rare earths, but it also dominates the production of inputs ranging from gearboxes and blades used in wind turbines to anodes and cathodes used in batteries and active pharmaceutical ingredients (APIs).
The concern is that, in the event of a conflict with another country, Beijing could use this position to disrupt supplies. The appropriate response is therefore to develop alternative sources of supply, without necessarily seeking to remove China from these supply chains altogether. The difficulty is that it may be hard for any one government to create viable alternatives. Developing sufficient capacity may therefore require coordinated action among allied countries.
The second concern is China’s dominance of technologies that could create security vulnerabilities for other countries. Here, the objective is not simply to diversify supply but, in some cases, to exclude China altogether. The decision by many Western governments to remove Huawei from 5G networks is one example.
Excluding Chinese technology presents a different challenge. National security concerns tend to centre on so-called “connected” devices that transmit or receive data. This is a rapidly expanding category of products, many of which are becoming embedded in critical infrastructure. That makes it difficult for governments to decide where to draw the line on Chinese involvement. And technological change means that whatever boundary is chosen is likely to shift quickly.
The costs of adjustment
All of this requires a different approach to thinking about economic policy. For much of the past three or four decades, economists have taken the supply side of the economy for granted. The received wisdom was that labour and capital should be organised to produce goods and services as efficiently as possible. We now also have to think about economic security and resilience.
This raises an obvious question: what is the cost of resilience? There is a trade-off between efficiency and resilience, but it would be wrong to assume that increasing resilience is always expensive.
In some cases, the costs can be surprisingly low. Following the Fukushima disaster in 2011, Toyota embarked on a programme to identify and remove single points of failure within its supply chains. The process was phased over several years and the company concluded that the impact on overall costs was manageable. A 2014 study by the academics Sunil Chopra and ManMohan S. Sodhi found that ‘for large companies in particular, building [supply chain] resilience is often relatively inexpensive, and in many cases it can be done without increasing costs”.
This contrasts with the much more significant costs imposed on European economies when they were forced to rapidly reconfigure their energy supplies following Russia’s invasion of Ukraine in 2022. The nature of the shocks was very different, so in some ways this is comparing apples and pears. But it illustrates a broader point: the costs of increasing resilience can be manageable if the adjustment is gradual and planned, but much greater when it has to be undertaken rapidly and under pressure.
The implications for government, firms and investors
What are the implications? For governments, it requires a different approach to economic policy. Decisions about the allocation of resources cannot be based solely on economic efficiency. They increasingly need to take account of national security and resilience. This will require working with allies to develop alternative sources of supply where building capacity domestically would be difficult or prohibitively expensive. It will also require governments to be explicit about the trade-offs they are willing to make in pursuit of greater resilience.
The green transition presents a particular challenge. China’s dominance of many green technologies means that governments may have to temper their climate ambitions if they want to significantly reduce their dependence on China.
This is not an argument for open-ended industrial policy or for governments to prop up failing firms. But there may be a case for supporting firms in genuinely critical sectors where doing so would help build resilient supply chains. A 2021 report by the European Commission identified semiconductor manufacturing, high-capacity batteries, critical minerals, pharmaceuticals, and cloud and edge computing assectors of concern. Firms operating in these sectors could benefit from government support while also becoming targets of Chinese retaliation.
For firms, the task is to identify where supply chains contain single points of failure and establish programmes to reduce them. The lesson from Toyota is that, if this process is spread over several years, the costs can be manageable.
For investors, China’s dominance of global production, and its ability to weaponise it to achieve geopolitical goals, represents another source of supply-side risk. Supply shocks tend to be stagflationary: they push up prices while reducing output. This is a toxic combination for investors because it can hit equities and bonds at the same time.
A conventional 60/40 equities/bonds portfolio may therefore offer less protection against these shocks than it did in the highly globalised world of the past few decades. This increases the case for diversification into other assets, including commodities, real estate and private assets.